Vietnam Income Tax for Remote Workers Paid Abroad: Nha Trang Guide (2026)
A resident is taxed on wages arising inside and outside Vietnam at 5% to 35%. A non-resident pays 20% on wages for work performed in Vietnam. A resident paid from abroad declares quarterly, directly with the tax authority, then finalises the year. Law 109/2025/QH15 applies to a resident's wages from the 2026 tax period.
On this page
- Short answer
- Resident or non-resident: which rules apply to you
- What counts as wages
- Resident: tax rates on salary
- Non-resident: 20% on wages for work done in Vietnam
- Freelance or business income instead of wages
- Who withholds tax and who declares
- How to declare and pay when you are paid from abroad
- The Khanh Hoa tax authority in Nha Trang
- Late filing, late payment and leaving the country
- If you already filed for 2026, and which rules replaced which
- Step by step
- Common questions
You live in Nha Trang and a company or clients abroad pay you. Article 2 of the Personal Income Tax Law decides whose income Vietnam taxes.
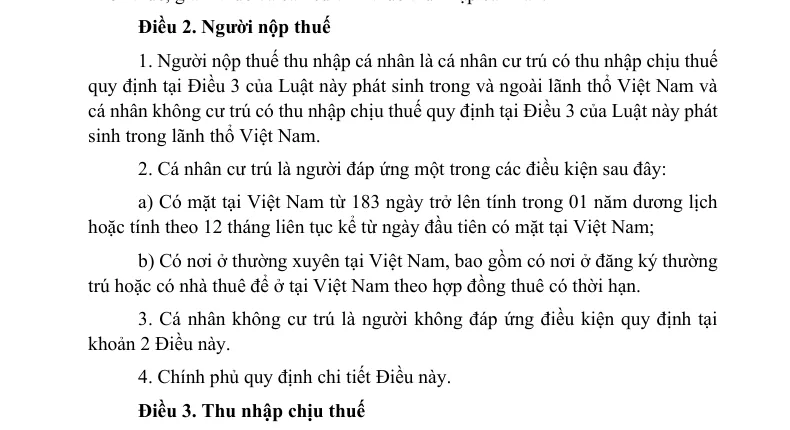
Người nộp thuế thu nhập cá nhân là cá nhân cư trú có thu nhập chịu thuế quy định tại Điều 3 của Luật này phát sinh trong và ngoài lãnh thổ Việt Nam và cá nhân không cư trú có thu nhập chịu thuế quy định tại Điều 3 của Luật này phát sinh trong lãnh thổ Việt Nam.
A resident individual is taxed on taxable income arising inside and outside Vietnam. A non-resident individual is taxed on taxable income arising within Vietnam.
Law 109/2025/QH15, Điều 2 khoản 1
Law 109/2025/QH15 takes effect from 1 July 2026. Its provisions on a resident’s wages apply from the 2026 tax period.
Short answer
- Rate: A resident is taxed at 5% to 35% on wages, including wages paid from abroad. A non-resident pays 20% on wages for work performed in Vietnam.
- Do now: Get a tax code within 10 working days of the date your personal income tax obligation arises. A resident paid from abroad then declares quarterly.
- Risk: A foreign individual with tax debt past the deadline can have exit suspended.
- Adviser: Ask a tax adviser if you are a non-resident working in Vietnam and abroad at once, or if you have foreign tax to credit.
This page summarises the legal text. It is not tax advice. Read it as the rule, then check your own facts.
Resident or non-resident: which rules apply to you
A resident individual meets one of the conditions in the Law. One is being present in Vietnam 183 days or more in a calendar year, or in 12 consecutive months from the first day of presence.
Another is a regular residence in Vietnam. That includes a registered permanent residence, or a home rented to live in under a lease with a fixed term. Leases whose terms total 183 days or more in the tax year count.
A person with a regular residence but under 183 days present is a resident if they cannot prove tax residency in any country. A non-resident is a person who does not meet the resident conditions.
For a resident, taxable income is income arising inside and outside Vietnam, regardless of where it is paid and received. For a non-resident it is income arising within Vietnam. Read the Vietnam tax residency explainer for how the days are counted.
What counts as wages
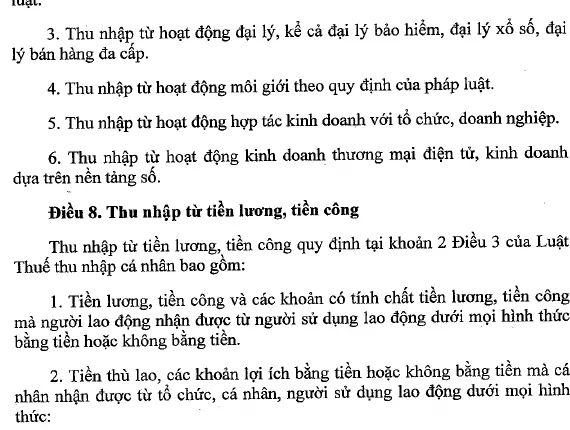
Wages and salaries include amounts an employee receives from an employer in any form, in cash or in kind. Payment for services also counts when you have no business registration and no business tax registration. That holds whether or not you hold a practising licence or certificate.
For tax, wage income is counted at the time the payer pays you or the time you receive it.
Resident: tax rates on salary
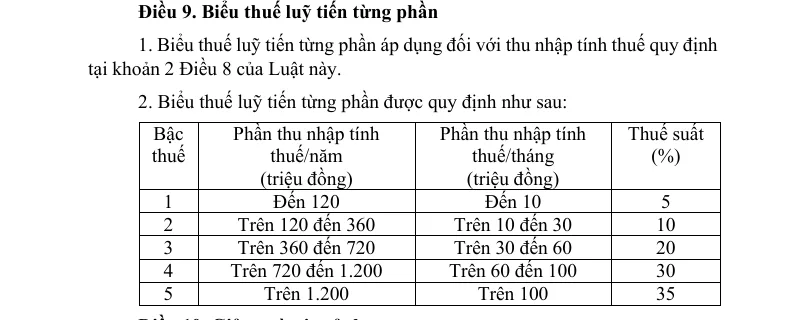
A resident’s wage tax is the taxable income, regardless of where it is paid, multiplied by the progressive rates. Taxable income is the total taxable wage income received in the tax period, minus listed deductions. The deductions include compulsory social, health and unemployment insurance contributions. They also include the deductions in Articles 10 and 11 of the Law.
| Portion of taxable income per year (million VND) | Per month (million VND) | Rate |
|---|---|---|
| Up to 120 | Up to 10 | 5% |
| Over 120 to 360 | Over 10 to 30 | 10% |
| Over 360 to 720 | Over 30 to 60 | 20% |
| Over 720 to 1,200 | Over 60 to 100 | 30% |
| Over 1,200 | Over 100 | 35% |
Tax is computed bracket by bracket: the part of taxable income in each bracket is multiplied by that bracket’s rate.
Family deductions
Family deductions are subtracted from taxable income before tax is computed on a resident’s wages. The deduction for you is VND 15.5 million a month (VND 186 million a year). Each dependant adds VND 6.2 million a month.
The Government submits deduction amounts to the National Assembly Standing Committee for each period’s conditions, so check the amount for your tax period.
Insurance you pay abroad
A resident with wage income abroad may deduct compulsory insurance premiums paid under the rules of the country where they pay them. The decree lists social, health and unemployment insurance, and professional liability insurance for certain occupations.
Non-resident: 20% on wages for work done in Vietnam
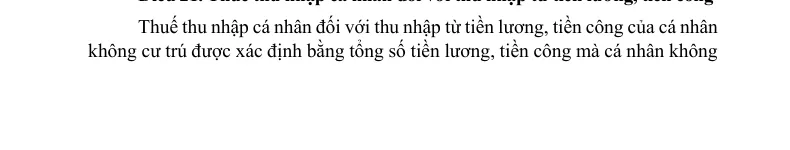
A non-resident’s wage tax is the total wages received for work performed in Vietnam multiplied by 20%, regardless of where the income is paid.
Thuế thu nhập cá nhân đối với thu nhập từ tiền lương, tiền công của cá nhân không cư trú được xác định bằng tổng số tiền lương, tiền công mà cá nhân không … cư trú nhận được do thực hiện công việc tại Việt Nam nhân (x) với thuế suất 20%, không phân biệt nơi trả thu nhập.
Tax on a non-resident’s wages is the total wages received for work performed in Vietnam, multiplied by 20%, regardless of where the income is paid.
Law 109/2025/QH15, Điều 21
Decree 253/2026/NĐ-CP restates the same rule. For a non-resident, the tax period is each time income arises.
Working in Vietnam and abroad at the same time
A non-resident who works in Vietnam and abroad at the same time, with Vietnam income that cannot be separated, uses a formula in the decree. For a foreign individual present in Vietnam, income arising in Vietnam equals days present in Vietnam divided by 365, times global pre-tax wage income. Other pre-tax taxable income arising in Vietnam is added.
Freelance or business income instead of wages
Payment for services counts as wages when you have no business registration and no business tax registration. Income from a registered business follows separate business rules, set out below.
A resident with business income at or below a level set by the Government pays no personal income tax. Decree 141/2026/NĐ-CP raised that figure in Decree 68/2026/NĐ-CP from VND 500 million to VND 1 billion.
Above the threshold and up to VND 3 billion a year, the rate is 15% on taxable income. You may instead pay a rate on the revenue above the threshold. For services that do not supply materials that rate is 2%.
A non-resident pays tax on the revenue multiplied by a rate. The rate for services is 5%. Revenue counts when it comes from supplying services in Vietnam, wherever the work is done.
For the visa side of working while here, read remote work on a tourist visa.
Who withholds tax and who declares
Organisations and individuals paying income withhold tax before paying it to the individual, except for some incomes listed in clause 4 of Article 67 of the decree. Payers include a Vietnamese party that reimburses wage costs to a foreign party.
If a foreign organisation not registered for tax in Vietnam pays you, or the payer has not withheld tax, you declare and pay the tax yourself.
How to declare and pay when you are paid from abroad
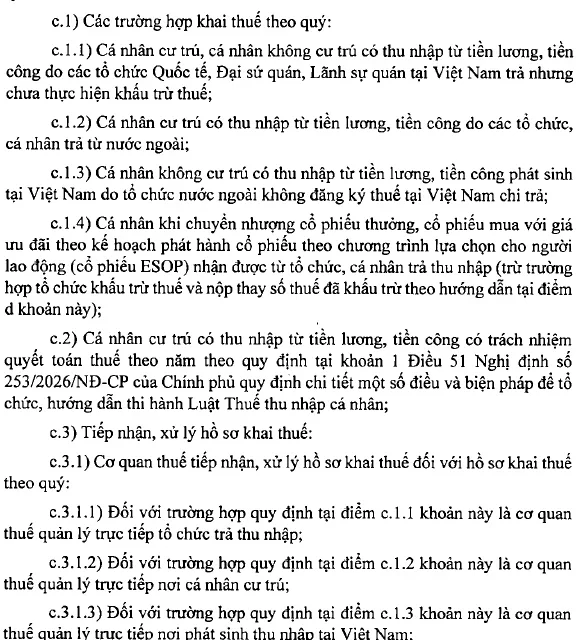
The circular sends a resident paid from abroad to quarterly filing.
c.1) Các trường hợp khai thuế theo quý: … c.1.2) Cá nhân cư trú có thu nhập từ tiền lương, tiền công do các tổ chức, cá nhân trả từ nước ngoài;
Quarterly declaration applies to a resident individual with wage or salary income paid by organisations or individuals from abroad, who declares directly with the tax authority.
Circular 89/2026/TT-BTC, Điều 22 khoản 1 điểm c.1.2
- Get a tax code. An individual who registers directly with the tax authority has 10 working days from the date the personal income tax obligation arises. Registration is electronic or automatic through the tax system. Write your tax code on documents when you declare and pay tax.
- Declare each quarter. As a resident paid from abroad, you declare quarterly, directly with the tax authority. A tax quarter runs from the first to the last day of the quarter.
- File with the right office. The return goes to the tax authority that directly manages your place of residence.
- Pay on time. If you calculate the tax yourself, pay it by the last day allowed for filing the return.
- Finalise for the year. A resident with wage income must finalise the year’s tax. The exception is tax payable smaller than tax already paid, with no request for a refund or offset against the next period.
Forms and deadlines
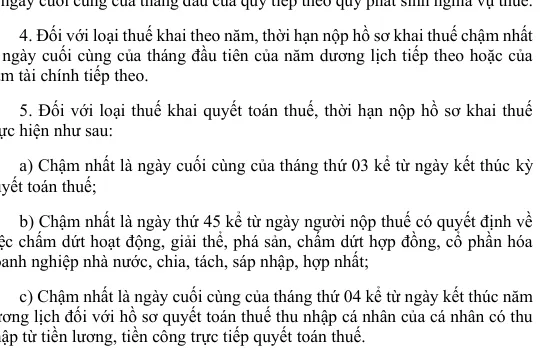
| Filing | Deadline |
|---|---|
| Quarterly return | Last day of the first month of the quarter after the quarter in which the obligation arises |
| Annual finalisation | Last day of the fourth month after the calendar year |
One return form covers residents and non-residents with wage income who declare directly. A resident’s annual finalisation has its own form, with an appendix for dependants.
First-year rule
For a resident, the tax period for wage income is the calendar year. Suppose you are present fewer than 183 days in a calendar year, but 183 days or more in the 12 consecutive months from your first day of presence. The first tax period is then those 12 months.
The finalisation deadline for that first year is the last day of the fourth month after the last day of the month in which the 12 months are complete.
Finalisation attachments
The attachments listed in Circular 89/2026/TT-BTC for a resident’s annual finalisation include these:
- Copies of the withholding proofs issued by the payer.
- For tax paid abroad where the foreign authority issues no tax-paid certificate, a bank-document copy confirmed by you.
- Documents proving the amount paid by the paying organisation abroad, for income received from abroad.
Currency and tax already paid abroad
Tax is declared and calculated in dong. Foreign-currency income is converted at the buying rate of the commercial bank holding the account used for the payment, at the time the income arises. If the payer holds no Vietnamese account, the State Bank of Vietnam central or cross rate at that time is used.
Where Vietnam has signed a double-taxation agreement with the country of payment, tax paid there is credited against tax payable in Vietnam, as the agreement provides. You file the proof of that tax with the finalisation declaration.
If you are a non-resident
Quarterly declaration also applies to a non-resident with wage income arising in Vietnam, paid by a foreign organisation not registered for tax in Vietnam. That return goes to the tax authority that directly manages the place where the income arises.
The Khanh Hoa tax authority in Nha Trang
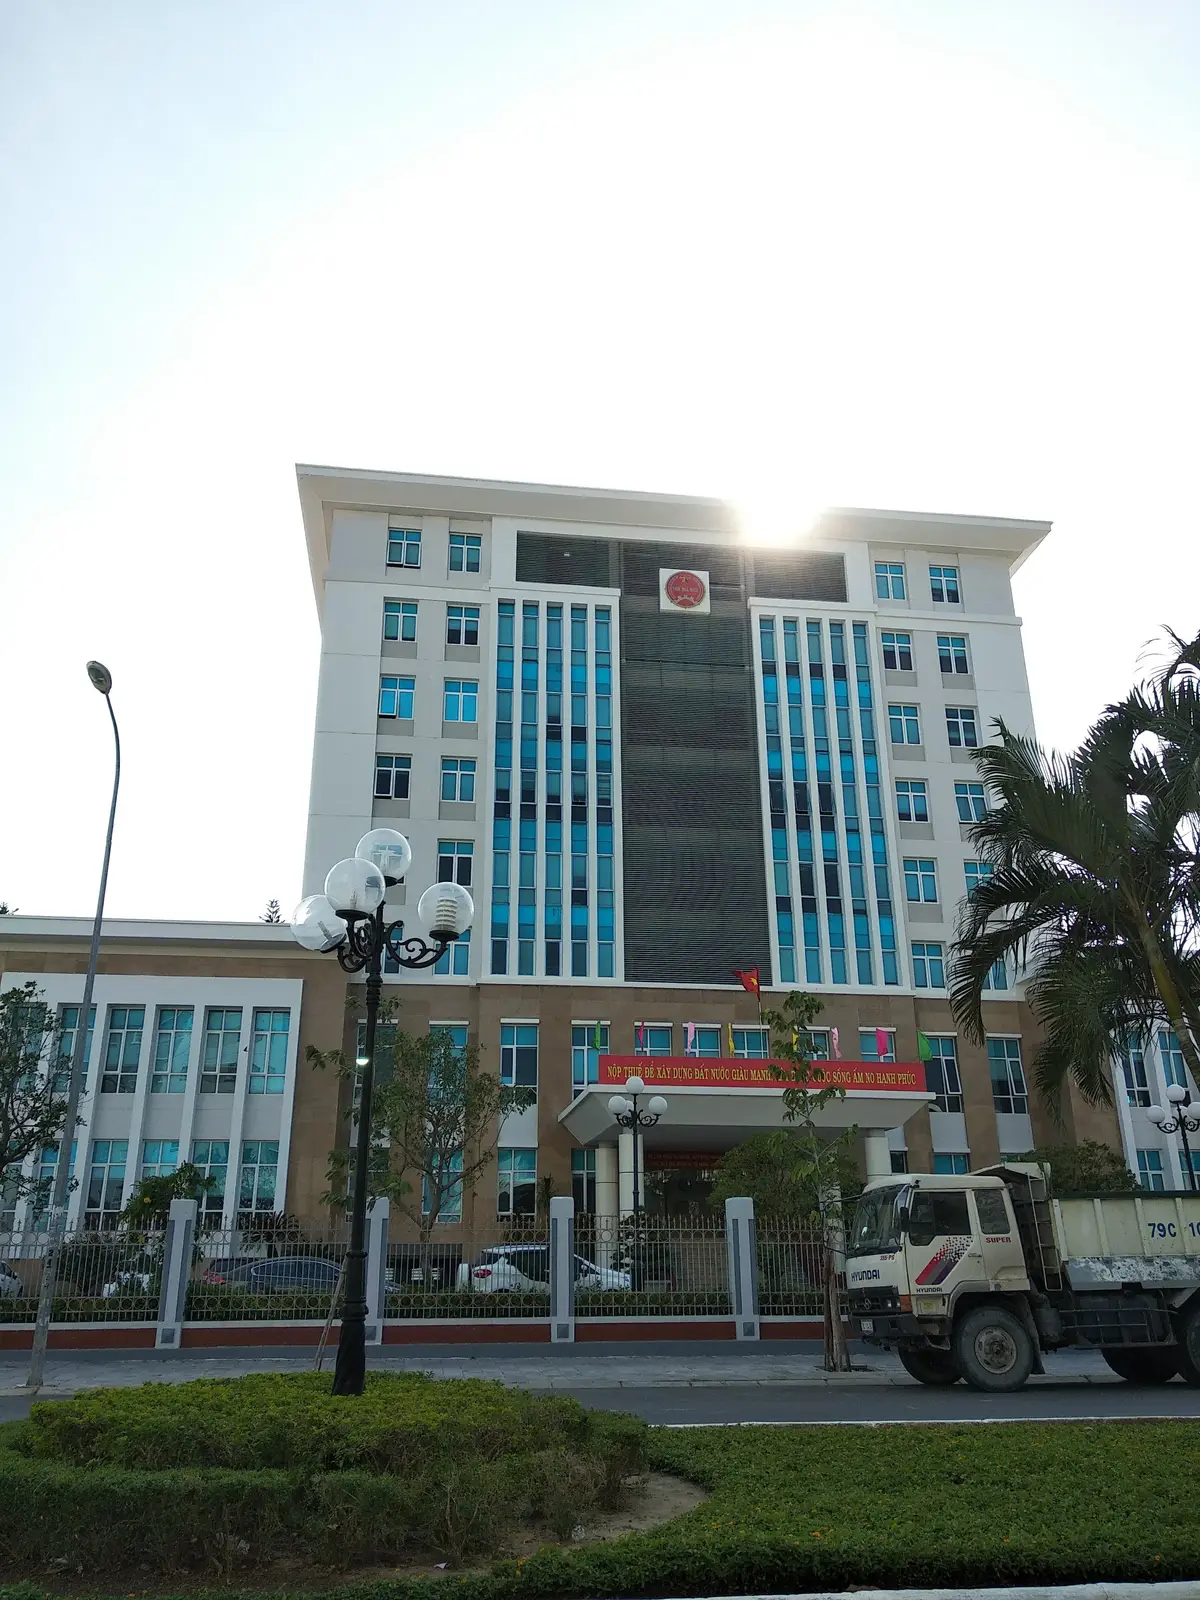
Your quarterly return goes to the tax authority that directly manages your place of residence. The Khanh Hoa provincial tax authority (Thue tinh Khanh Hoa) runs its own website.
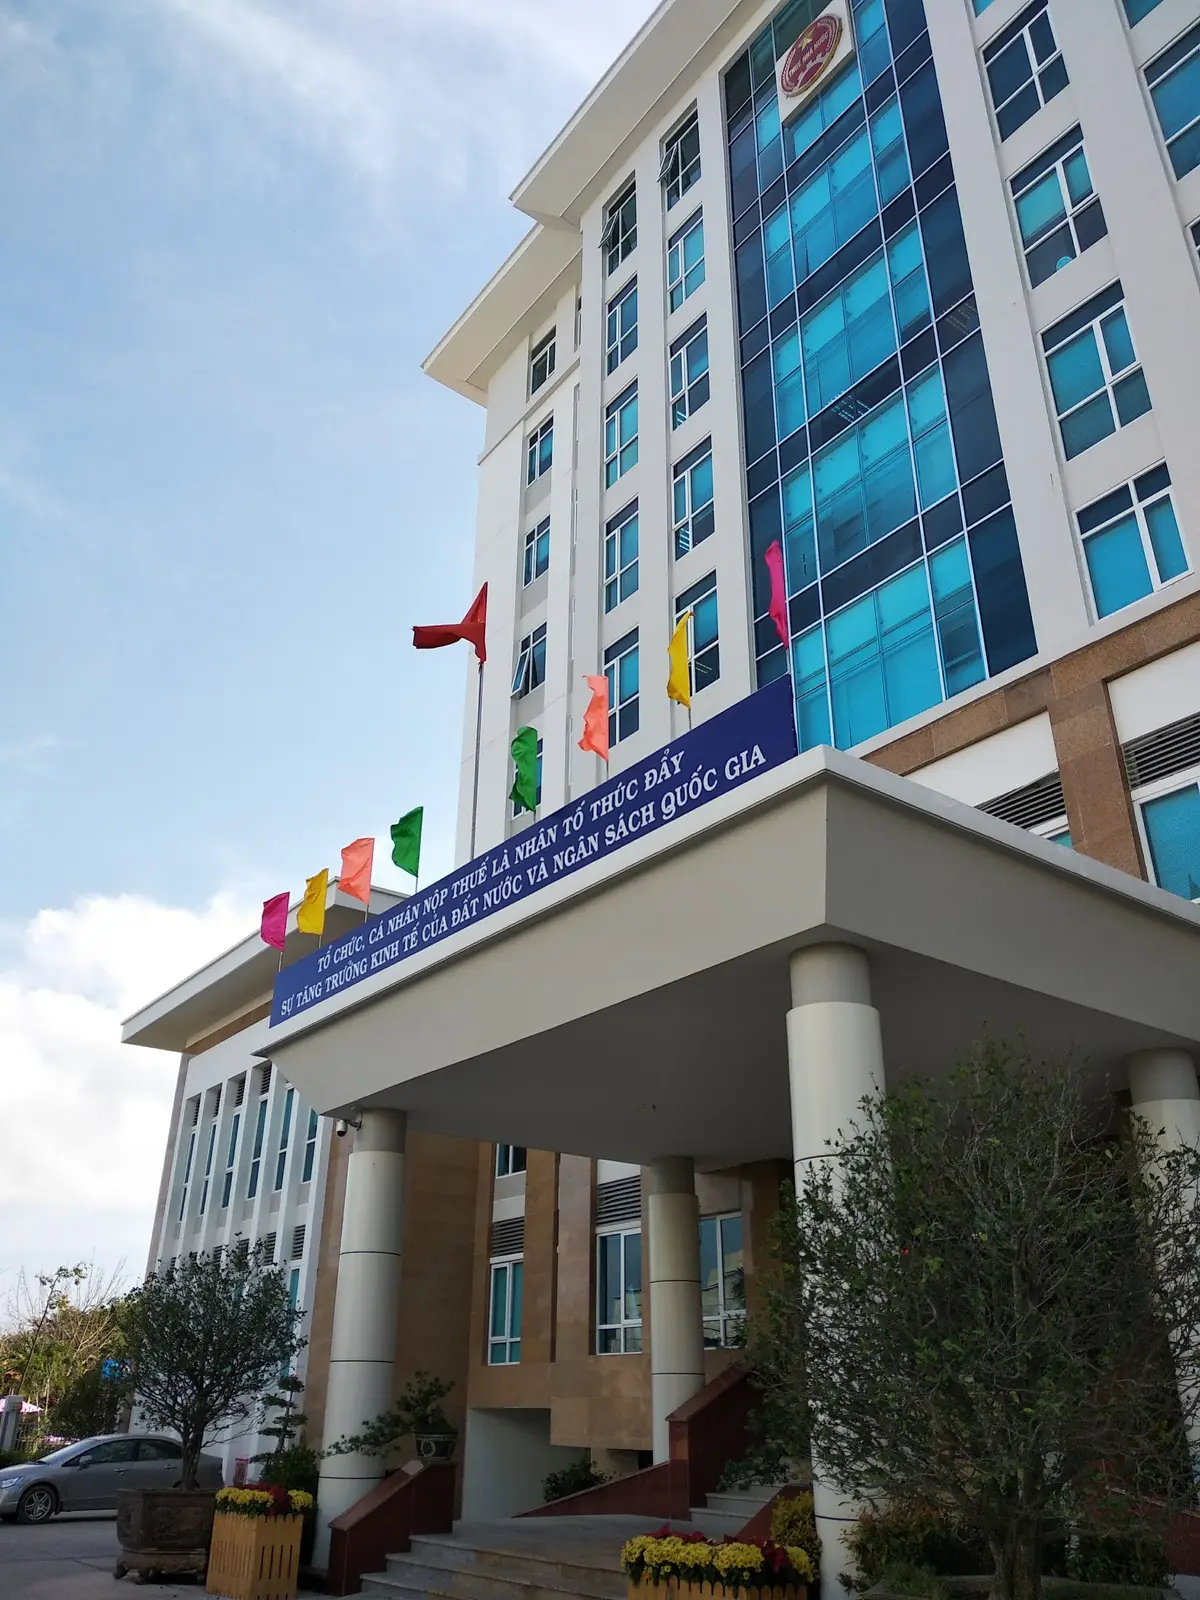
Its own website gives the address as 17 Street 19/5, Vinh Diem Trung urban area, Tay Nha Trang Ward, Khanh Hoa Province. The telephone shown is (0258) 3824372. The footer gives one address and no ward list, so ask which office covers your ward before you go.

For wage income paid from abroad, an explainer of 13 May 2026 gave the first-registration filing place. That place is the provincial or city tax authority where the work arises in Vietnam. It predates Circular 89/2026/TT-BTC, so confirm with the office.
The same explainer lists a copy of a valid passport for a foreign national without a personal ID number from the national population database.
Late filing, late payment and leaving the country
Late-payment interest is 0.03% per day on the late-paid tax managed by the tax authority. It runs from the day after the payment deadline to the day before the tax is paid into the state budget.
A foreigner who has not completed tax obligations must complete them before leaving Vietnam. A foreign individual with tax debt past the deadline can have exit suspended.
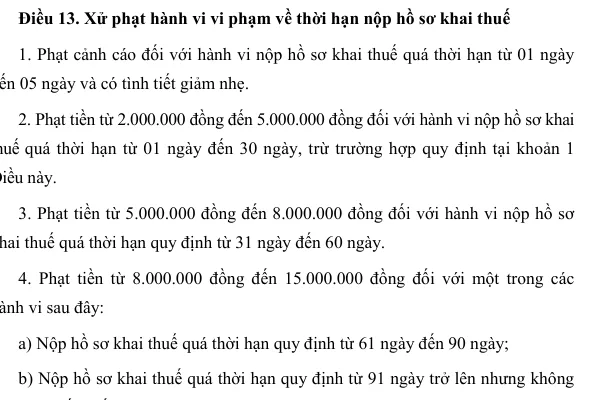
Decree 125/2020/NĐ-CP, as amended, stays in force from 1 July 2026 until a replacement is issued. The fine amounts in its Article 13 are fines for organisations.
| Days late filing a tax declaration | Fine for an organisation |
|---|---|
| 1 to 5, with a mitigating circumstance | Warning |
| 1 to 30 (other cases) | VND 2,000,000 to 5,000,000 |
| 31 to 60 | VND 5,000,000 to 8,000,000 |
| 61 to 90 | VND 8,000,000 to 15,000,000 |
| Over 90 days, tax payable, tax and interest paid in full before an inspection or violation record | VND 15,000,000 to 25,000,000 |
For the same violation, an organisation’s fine is twice an individual’s, except for acts in Articles 16, 17 and 18. So an individual who files late faces half the amounts above.
If you already filed for 2026, and which rules replaced which
If you filed and paid 2026 wage tax between 1 January 2026 and the day Decree 253/2026/NĐ-CP took effect, you do not re-file monthly or quarterly returns. You adjust the amounts in the 2026 annual finalisation declaration.
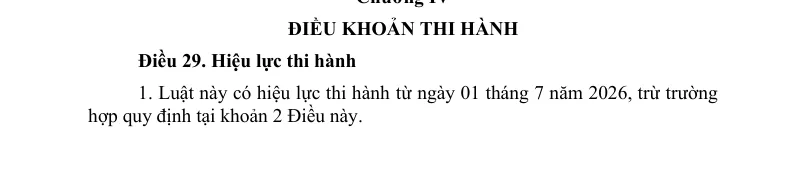
Law 04/2007/QH12 is replaced by the new Law: it ceased to be effective when the new Law took effect, and its resident wage provisions ceased from the 2026 tax period. The tax-administration Law 108/2025/QH15 takes effect on 1 July 2026.
Related guides: social insurance for foreigners, opening a bank account in Nha Trang and the money hub.
Photos and clips uploaded to Google Maps (Khanh Hoa Tax Authority on Google Maps (opens in a new tab)) by @CHUP HINH NHA TRANG.
Step by step
- Get a tax codeRegister electronically, within 10 working days of the date the personal income tax obligation arises.
- Declare each quarterA resident paid from abroad declares quarterly, directly with the tax authority.
- File with the right tax authoritySend the return to the tax authority that directly manages your place of residence.
- Pay on timeIf you calculate the tax yourself, pay it by the last day allowed for filing the return.
- Finalise for the yearFile the annual finalisation by the last day of the fourth month after the calendar year.
Not confirmed: Which Khanh Hoa tax office takes your quarterly return: the rule names the office that directly manages your place of residence. The provincial site gives one address with no ward list. Ask the office before filing. How the quarterly amount is computed and settled at year-end: ask the office or a tax adviser before your first return.
Common questions
Can I deduct social insurance I pay in my home country?
A resident with wage income abroad may deduct compulsory insurance premiums paid under the rules of the country where they pay them. The decree names social, health and unemployment insurance and professional liability insurance for certain occupations.
Which currency do I declare in, and how is foreign pay converted?
Tax is declared and calculated in dong, and the Government sets the cases that may use a foreign currency. Foreign-currency income is converted at the buying rate of the commercial bank holding the account used for the payment, at the time the income arises. With no Vietnamese account on the payer's side, the State Bank of Vietnam rate at that time applies.
When does my salary count as income?
Wage income is counted at the time the payer pays you or the time you receive it.
Can I leave Vietnam with tax unpaid?
A foreigner who has not completed their tax obligations is among the cases that must complete them before leaving Vietnam. A foreign individual with tax debt past the deadline can have exit suspended.
I already filed for 2026 under the old rules. Do I file again?
If you filed and paid wage tax between 1 January 2026 and the day Decree 253/2026/NĐ-CP took effect, you do not re-file the monthly or quarterly returns. You adjust the amounts in the 2026 annual finalisation declaration.
Do I need a tax code to file?
An individual who registers tax directly with the tax authority has 10 working days from the date the personal income tax obligation arises. Write your tax code on documents when you declare and pay tax.
Where in Nha Trang is the tax authority?
The Khanh Hoa tax authority's own site gives 17 Street 19/5, Vinh Diem Trung urban area, Tay Nha Trang Ward. The telephone shown is (0258) 3824372.
What is the late-payment interest rate?
0.03% per day on the late-paid tax amount managed by the tax authority. Interest runs from the day after the payment deadline to the day before the tax is paid into the state budget.
Read next
General information checked against the sources listed above, not legal advice for your situation. Rules and office practice change; confirm with the immigration office or a licensed adviser before you act. See how guides are checked.
Spotted an error? Report it.